Fintech & payments
We take payment on unattended devices — cash, card, QR — and reconcile daily takings against what reached the account. 14M transactions.
Case
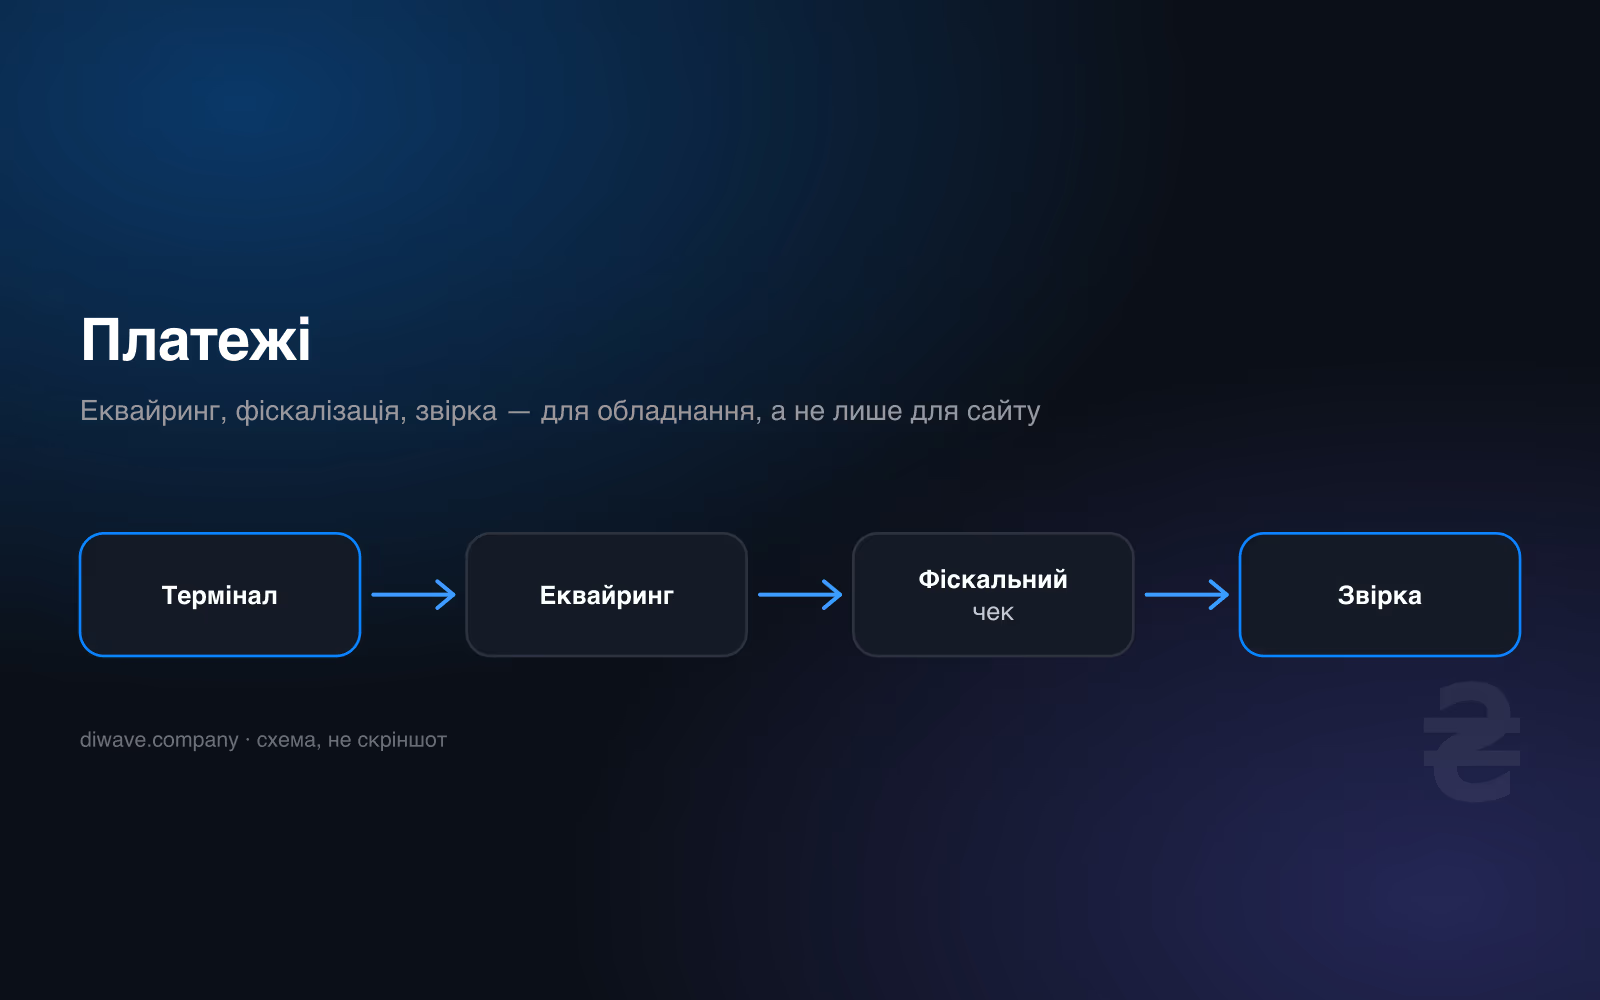
Self-service equipment has to take money and issue a fiscal receipt with no cashier present. We build the layer between the device and the bank: card and cash acceptance, the fiscal registrar and a receipt that reaches the customer instead of staying in the machine's memory.
Every transaction is tied to a device and a shift, so reconciling takings is a report rather than an audit. The equipment keeps working offline, and the transactions catch up with the server once the connection returns.
This is how the self-service car washes, vending machines and terminals we have connected work.
Where money disappears in payments
Taking payments is the easy part; what follows is hard. How much came in cash, how much by card, how much is stuck in incomplete transactions, and why the shift total is off by a few hundred. Without data from the device itself this cannot be untangled.
The second problem is taking money where there is no cashier. The device stands outdoors, runs around the clock, and must reliably take payment, deliver the service, and record both events so they can be reconciled later.
What we do
Unattended payment acceptance
Bill and coin acceptors, contactless terminals, QR payment from a phone with no app to install.
Revenue reconciliation
What the device accepted matched against what reached the account. Shift discrepancies surface the same day, not at month end.
Incomplete transactions
Paid but not delivered, or the reverse — logged separately and raising an alert.
Acquiring integration
Connection to bank processing, receipts and fiscalisation where required.
Device-level fraud checks
Enclosure opening, counter resets, mismatch between dispensed and paid — all recorded.
Owner reporting
Revenue per site and per device, trends, payback on each unit.
What it runs on
MDB and ccTalk for payment peripherals, integration with bank acquiring, Modbus to talk to the equipment controller. Node.js and PostgreSQL on the server. We do not build banking products and do not work with cryptocurrency: our part is taking payment at the device and accounting for it honestly.
Our evidence
Over 14 million payment transactions processed by the self-service car wash network system. Years under load, cash and cards together, reconciled daily.
Frequently asked
Do you build a payment service?
Can we take payment without a terminal?
What about fiscalisation?
Do you accept cryptocurrency?
Answers on this topic
Plain explanations without marketing — useful even if you never hire us.
Wero and ENP: what changes for unattended terminals
Europe is building its own account-to-account payment network, ENP and Wero. What it means for car washes and vending, and how to prepare now.
EU PSR: the Council position and unattended payments
On 29 Oct 2026 the EU Council unanimously adopted its PSR position: IBAN–name checks, spoofing liability, phone features for third-party apps. What it means.
Car wash payments: from the bay controller to reconciliation
How payments work at a self-service car wash — coins, notes, cards and QR — what has to be reconciled every day, and where the revenue quietly leaks.
Fiscal receipts from a terminal with no cashier
How a receipt reaches the tax authority from an unattended terminal: who issues it, when, what happens when the link drops, and where the gap usually appears.
Card payments for vending machines without a cashier
MDB reader, bank terminal or QR: three ways to take cashless payments on a machine, fiscal receipts without a cashier, per-machine reconciliation, offline mode.